
What to do next?
Buying your first home is a major milestone, but it isn't the finish line for KiwiSaver. Your KiwiSaver savings have helped with one goal. Now it's starting another.
Three simple things worth checking.
Contribution rate
Check what you’re contributing still suits your budget and longer-term goals. A small increase today could make a difference over time.
Your fund
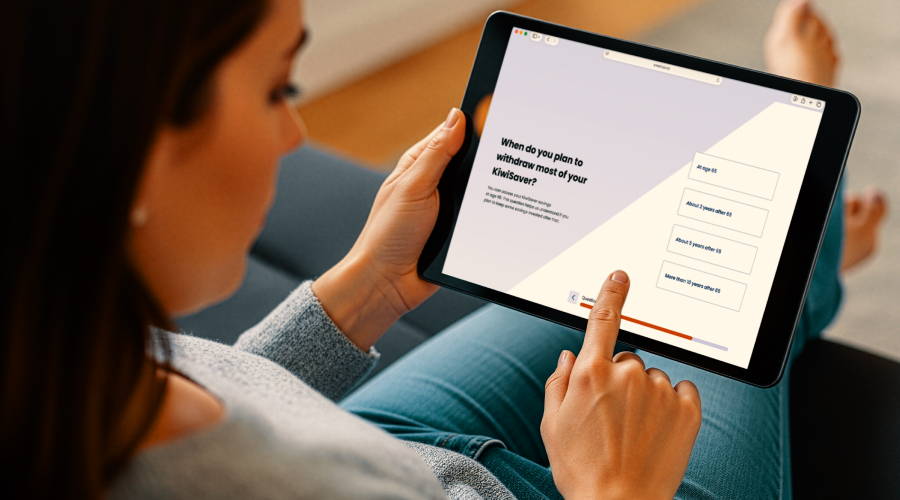
Your goal and timeframe have changed. It’s worth checking whether your fund still suits them.
Your progress
Keep track of your balance and contributions through the Smart Invest app or member portal.
Start with your contribution rate
A first home withdrawal can leave your balance looking very different. That’s expected. What matters now is rebuilding momentum to grow it again.
Check what you’re contributing and consider whether your current rate still suits your budget. Even a small increase can make a big difference over time.
Common questions
Explore common questions people ask about KiwiSaver after using it for their first home.
Usually, yes. If you’re employed and contributing through your pay, your contributions generally continue after the withdrawal. A first-home withdrawal doesn’t pause them or close your account.
Possibly. Your goal has just shifted from a near-term withdrawal to a longer-term retirement saving, and your fund should generally reflect the timeframe you're investing for. Our Fund Finder is a quick way to check.
Your account remains open and starts from the balance left after your withdrawal.
No. Making a first-home withdrawal doesn’t change your contribution rate – it generally stays as it was unless you choose to change it.
No. A KiwiSaver first-home withdrawal can only be used once. From here, your KiwiSaver saving’s main purpose is to support you in retirement.
Can't find what you're looking for? Check out our FAQs page.


