
What is KiwiSaver?
KiwiSaver helps you build your savings for two of life’s big goals: buying your first home and funding your retirement.
It’s made up of contributions from you and, if you're employed and eligible, your employer. You may also qualify for a government contribution.
The money is invested in a fund, giving it the opportunity to grow over time.
How KiwiSaver works?
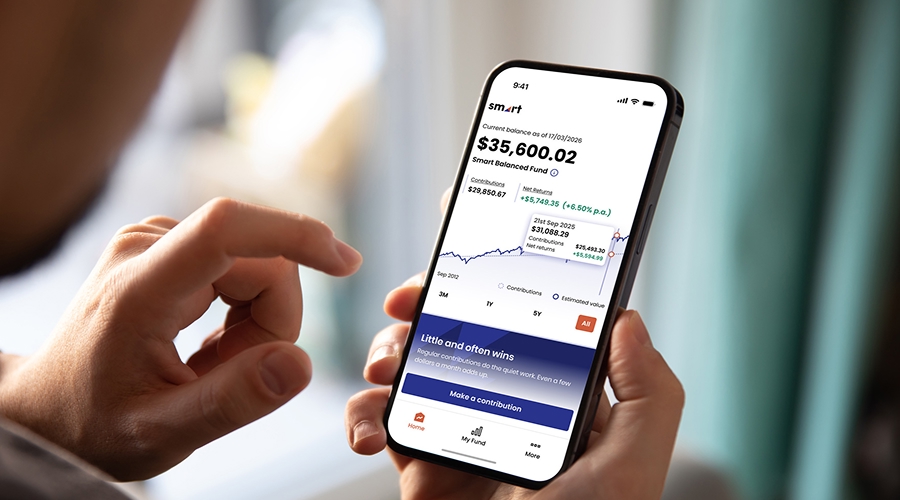
KiwiSaver at different stages of life
Your plans can change what you need from your KiwiSaver savings.
Common questions
Explore common questions people ask about KiwiSaver.
For many people, it can be. KiwiSaver helps you build long-term savings, and your own contributions may be topped up by your employer and, if you qualify, the government. Like any investment, though, returns aren’t guaranteed and your balance will rise and fall over time.
Usually, not whenever you like. KiwiSaver is designed for long-term saving, so you can generally access your money from age 65. You may be able to withdraw it earlier in some situations, including buying your first home, significant financial hardship or serious illness.
Not quite. The money you contribute is your own savings. If you’re eligible, your employer usually contributes too, and if you qualify[DY1] the government can add 25 cents for every dollar you put in, up to $260.72 a year. You don’t need to contribute the full $1,042.86 to receive something — contribute less and you may still get a smaller government contribution.
Your KiwiSaver savings become part of your estate and are handled along with your other assets.
Can't find what you're looking for? Check out our FAQs page.
KiwiSaver is a long game. We’re in it for the duration.
Smart is part of NZX, the company behind New Zealand’s stock exchange. We’ve been helping New Zealanders invest for more than 30 years.
Our approach is simple: time in the market, diversification and the fees you don’t pay. Because investing isn’t just about what you earn. It’s also about what you keep working for you.
